Unlocking credit: The alternative data expanding access to business loans
We’ve long felt that unlocking credit in African markets is key to empowering businesses and driving consumer spending in African markets. Last year we looked at the story from two lenses:
- Consumer credit - How EcoCash could have been Zimbabwe’s credit scoring saviour
- Country credit financing - Will the African Union’s Credit Rating Agency solve continental financing woes?
This year we highlighted the need for participants in housing markets in the (SADC) region to encourage lenders to take on more risk when giving loans. So yes, we’re pretty convinced that the lack of effective credit-scoring systems is holding back African economies.
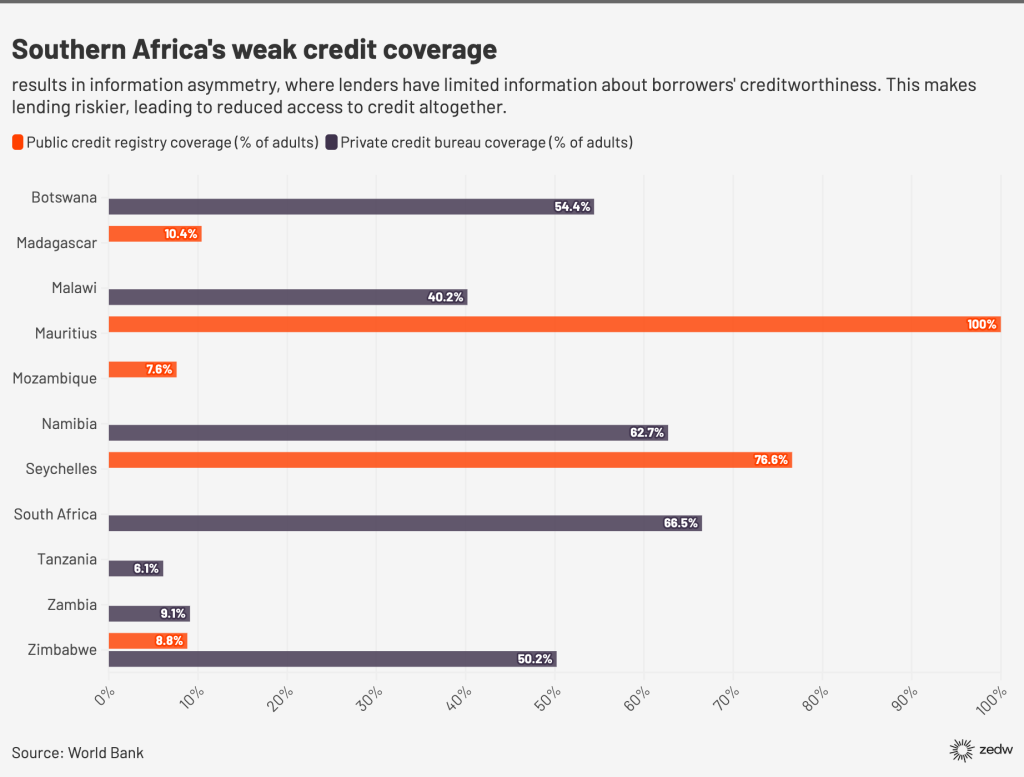
Outside of Mauritius, Seychelles and South Africa, most countries in SADC have glaring gaps in their credit coverage
The Alliance for Financial Inclusion (AFI) recently released a report titled Alternative Data for Credit Scoring. The report puts forward some of the solutions that can be used in order to create credit scoring systems for MSMEs in countries that don’t have reliable credit bureaus. This analysis will touch on a few of these models that we found particularly interesting along with highlighting why these may be more effective than the traditional methods currently used to identify borrowers.
Tagged: Africa Union Credit Rating Agency (ACRA), Alliance for Financial Inclusion (AFI), Alternative Data for Credit Scoring, Angola, Central Bank of Seychelles, Central Privada de Informacao de Credito SA, credit, credit bureau, Credit Reporting Act, Creditworthiness, EcoCash, Financial Inclusion